
Premium Only Plan (POP) vs. a Full Section 125 Savings Plan
By Tax Benefit Strategies | Published October 30, 2026 | Updated November 2026 | 5 min read
A premium only plan (POP) is the simplest kind of Section 125 plan. Many employers already have one, often set up by their payroll provider or benefits broker.
A POP does save payroll taxes, but only on the health premiums employees pay. Here is how a POP works, what it saves, and how a full Section 125 savings plan compares.
What Is a Premium Only Plan (POP)?
A premium only plan (POP) is a Section 125 plan that does one thing: it lets employees pay their share of employer-sponsored health premiums with pre-tax dollars. The premiums come out of pay before income tax and FICA tax.
A POP usually covers the employee share of group medical, dental and vision premiums. Like every Section 125 plan, it needs:
- A written plan document that sets out the plan rules
- Nondiscrimination rules, so the plan does not favor highly compensated employees
- Annual elections, with changes during the year only for qualifying life events
For the other plan types, see our Section 125 cafeteria plan guide.
What Does a POP Save an Employer?
A POP saves the employer 7.65% in FICA tax on every premium dollar employees pay pre-tax. The savings depend on two numbers: how many employees are on the health plan, and how much each one pays toward premiums.
Example: A company has 50 employees. 25 of them are on the group health plan and each pays $150 a month toward premiums.
- Pre-tax premiums: 25 × $150 × 12 = $45,000 a year
- Employer FICA savings: $45,000 × 7.65% = about $3,440 a year
The other 25 employees add no savings, because they pay no premiums through the plan.
Where a POP Stops
- Only enrolled employees count. In companies with many hourly workers, a large share of employees often waive group coverage.
- Savings are capped by premiums. The employer saves only on the premium dollars employees already pay.
- Employees get no new benefits. A POP changes how premiums are paid, not what employees receive.
How Does a Full Section 125 Savings Plan Compare?
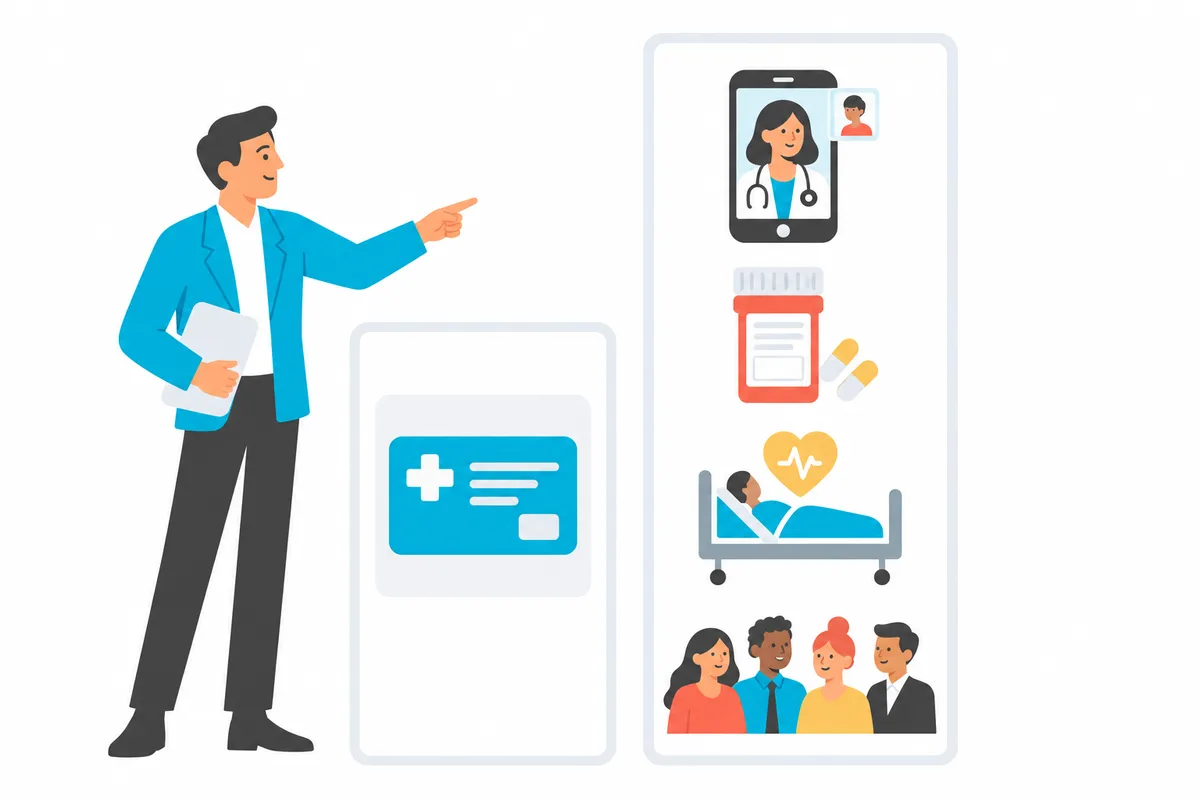
A full Section 125 savings plan includes every employee, not only those on the health plan. It adds employee benefits that are paid pre-tax, so the payroll tax savings apply across the whole workforce.
| Premium Only Plan (POP) | Full Section 125 Savings Plan | |
|---|---|---|
| Who takes part | Only employees on your group health plan | Every employee, automatically enrolled and free to opt out |
| Employer savings | 7.65% of the premiums employees pay | Most employers save $650–$850 per employee per year |
| Example: 50 employees, 25 on the health plan | About $3,440 a year | About $32,500 a year |
| New benefits for employees | None | Unlimited virtual care with no copay, $0-copay generic prescriptions, hospital indemnity cash benefits |
| Employee take-home pay | Higher only for employees on the health plan | Typically rises about 4–6% |
| Cost to set up | Many providers charge for the plan document and renewals | No setup fee, no plan-document charge, no minimum contract |
Our program works alongside your existing health plan. It does not replace it. The program fee is a per-employee monthly fee paid from the payroll tax savings, so the employer does not pay out of pocket. See what a Section 125 plan costs an employer and the full benefits list.
Get a free savings estimate based on your employee count.
Get Your Savings Estimate →Which One Fits Your Business?
A POP can be enough if you have fewer than 50 employees, or almost all of your employees are on the group health plan and you only want their premiums paid pre-tax.
A full Section 125 savings plan fits better if you have 50 or more employees, many of your employees are hourly or waive group coverage, and you want to add benefits without adding cost. The program is available in 40 states; see state availability.
Estimate your savings to compare the numbers for your business.
Frequently Asked Questions
What is a premium only plan?
A premium only plan (POP) is the simplest Section 125 plan. It lets employees pay their share of employer-sponsored health insurance premiums with pre-tax dollars.
Is a POP the same as a Section 125 plan?
A POP is one type of Section 125 plan. A Section 125 plan, also called a cafeteria plan, can also include other benefits, such as FSAs and hospital indemnity coverage.
How much does a POP save an employer?
A POP saves the employer 7.65% in FICA tax on each premium dollar employees pay pre-tax. If 25 employees each pay $150 a month in premiums, that is about $3,440 a year.
Do we need 50 employees for a full Section 125 savings plan?
For our program, yes. It requires at least 50 employees. Owners with more than one location can count employees across all their locations.
Sources
The rules and figures on this page come from these sources.
- Cafeteria plans: 26 U.S.C. § 125
- Benefits a cafeteria plan can include: IRS Publication 15-B
- FICA wage exclusion: 26 U.S.C. § 3121(a)(5)(G)
- FICA and FUTA rates: IRS Publication 15
This article is general information, not tax or legal advice. Talk to your tax advisor about your situation.